×
Back to menu
HomeBlogBlogTeen Credit-Building Checklist: Start With Money Habits

Teen Credit-Building Checklist: Start With Money Habits

Teen Credit-Building Checklist: Start With Money Habits

25% off on product page · save $1.66

Teen Credit-Building Checklist: Start With Money Habits

Nathan Brown · 6 min

Teen Credit-Building Checklist: Start With Money Habits

Start with habits that make credit easier to manage

Choose a small savings goal and record money coming in and going out for a month. Include occasional purchases, not just regular expenses. If you are helping a teen, review the numbers together and ask what would need to change to afford a monthly payment without using savings meant for emergencies.

Next, practice due dates. A teen might pay a phone bill or reimburse a parent for an agreed-upon expense. Set a calendar reminder before the due date, then confirm the payment went through. These payments may not appear on a credit report, but the routine is useful when a reported account becomes an option.

It also helps to separate three ideas: a credit report records certain account and borrowing activity; a credit score is calculated from information in a report; and a debit card or savings account does not, by itself, establish credit. Before treating any payment as a credit-building step, find out whether it is reported to a credit bureau.

Choose a step that fits your age and budget

If you are under 18, a parent may be able to add you as an authorized user. Ask the issuer whether it permits your age and reports authorized-user activity. Review the primary account’s payment history and balances first: missed payments or high balances could work against your goal.

At 18 or older, you can consider an eligible starter or secured card if you can manage its payments. Compare fees, interest, grace-period terms, any required deposit, and credit-bureau reporting. A secured-card deposit does not pay the monthly bill.

Featured in this guide

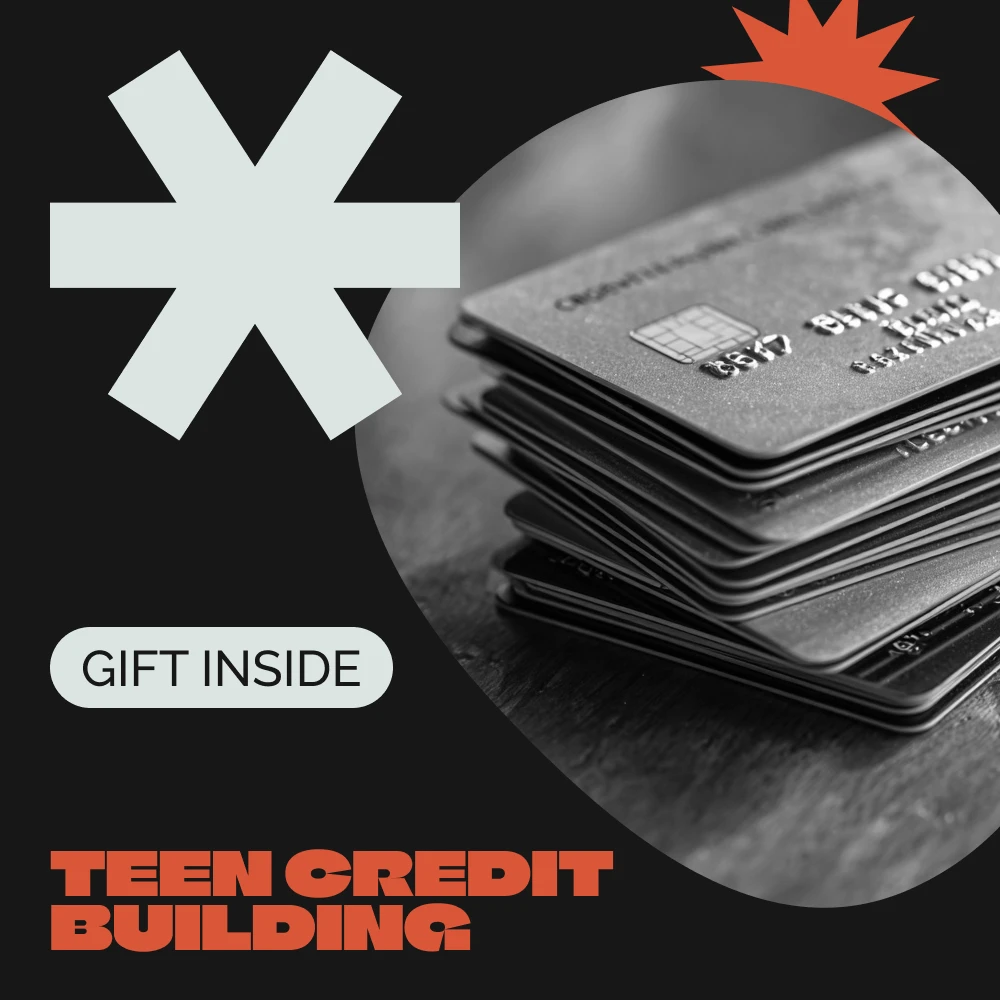
Teen Credit Building Checklist 💳 | Printable Financial Guide for Beginners | How to Build Credit as a Teenager | Teen Money Management PDF

View product

Four questions to answer together

Use our printable Teen Credit Building Checklist to keep the conversation focused on what you can manage now.

  • Whose account is it? Identify the primary cardholder and who is responsible for payment. An authorized user is not the primary cardholder.
  • What can you repay? Base a spending limit on money you already have, without drawing on emergency savings.
  • When is payment due? Set a reminder, review the statement, and confirm payment went through. Paying the statement balance in full can help avoid purchase interest when the card’s grace-period terms apply.
  • What gets reported? Confirm the provider’s reporting policy. A debit card or savings account does not, by itself, establish credit.

Planning purchases is part of protecting that budget. Our wardrobe-planning guides are optional tools for thinking through clothing purchases, not a credit-building requirement.

Understand what a report can tell you

A credit report records certain reported account activity; a credit score is calculated from information in a report. If you have never had a reported account, you may not have a report yet. That is not the same as having a poor score.

When it is appropriate to review your report, you can request free reports through AnnualCreditReport.com. Read the account details and dispute inaccurate information. Keep budgeting and saving alongside any credit-building plan.

Check the product’s listed specifications when evaluating understand what a report can tell you.

Watch the Teen Credit Building Checklist 💳 | Printable Financial Guide for Beginners | How to Build Credit as a Teenager | Teen Money Management PDFWatch the Teen Credit Building Checklist 💳 | Printable Financial Guide for Beginners | How to Build Credit as a Teenager | Teen Money Management PDFproduct video

Watch · product page video

“As a mom, I found this guide very helpful”

Obsessian product page · Product review

View product

FAQ

Can I build my minor child’s credit?

You may be able to add your child as an authorized user if the issuer permits it and reports the activity, but results vary. A minor generally cannot open a credit card independently.

Can a 16 year old start building credit?

Possibly, through an issuer-permitted authorized-user arrangement, although reporting and scoring outcomes vary. A 16-year-old generally cannot open a credit card independently, so money habits should remain the priority.

How long does it take to build a credit score from 500 to 700?

There is no reliable universal timeline; it depends on the report and what caused the current score. Review reports for errors and focus on on-time payments and manageable balances rather than a promised quick increase.

See if Teen Credit Building Checklist 💳 | Printable Financial Guide for Beginners | How to Build Credit as a Teenager | Teen Money Management PDF fits your setup

View product

Leave a comment

Why obsessian.com?

Uncompromised Quality
Experience enduring elegance and durability with our premium collection
Curated Selection
Discover exceptional products for your refined lifestyle in our handpicked collection
Exclusive Deals
Access special savings on luxurious items, elevating your experience for less
EXPRESS DELIVERY
FREE RETURNS
EXCEPTIONAL CUSTOMER SERVICE
SAFE PAYMENTS
Top

Shopping cart

×