10% off on product page · save $1.11
How Much to Budget for Living Expenses: A Practical Plan
Start with your actual take-home income
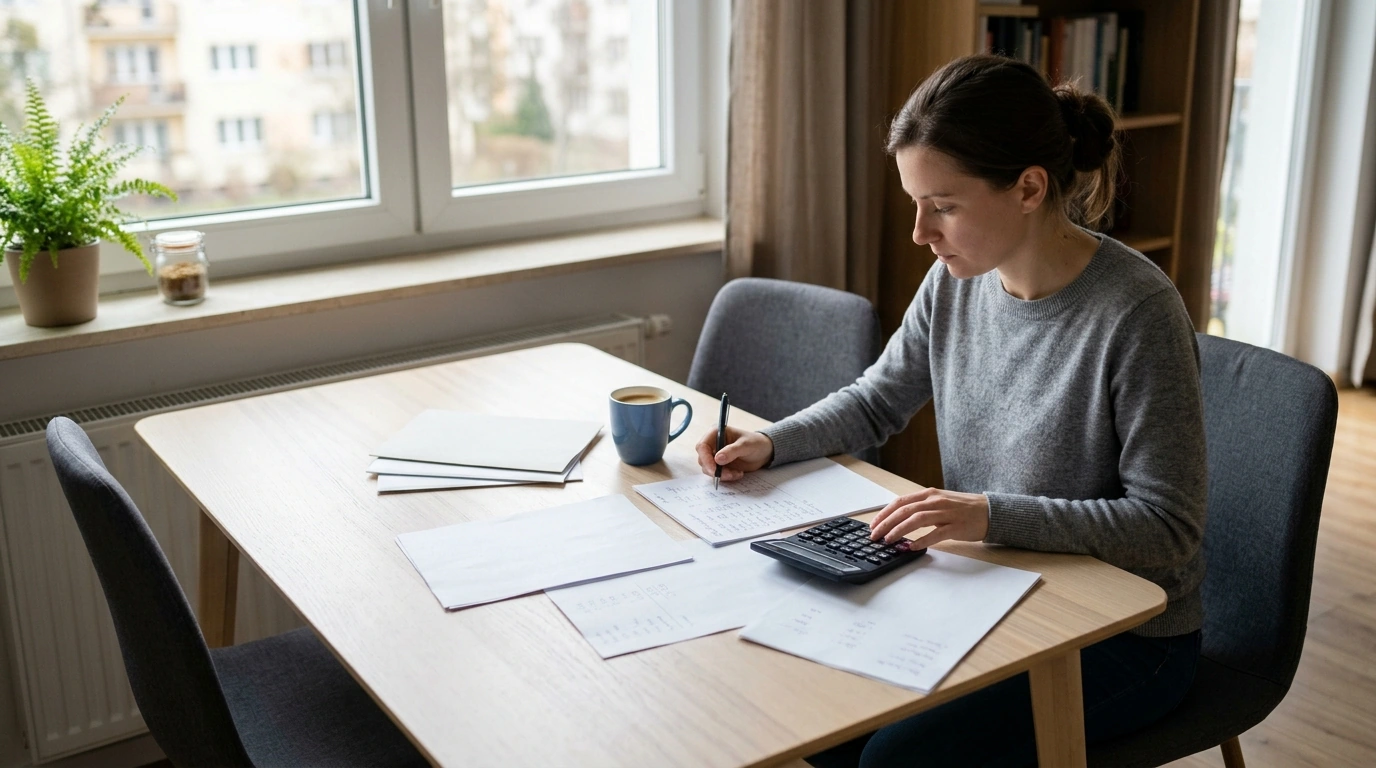
Begin with the amount deposited into your account after taxes and payroll deductions, rather than your gross salary. If you have more than one income source, add the take-home amounts together. This gives you a realistic ceiling for the expenses in your plan.
If your income changes from month to month, review several recent months and choose a conservative amount to plan around. When you earn more, you can use the difference for an upcoming bill or a cash cushion instead of assuming every month will be equally strong. You can revise the number as your circumstances change.
Build your living-expense baseline
Use bills and recent statements to total essentials such as housing, utilities, groceries, transportation, healthcare, insurance, and minimum debt payments. Add flexible spending separately. Include less-frequent costs—such as repairs and annual fees—at their estimated monthly share.
Fill in your own amounts below. The blanks are not recommended spending targets.
| Expense group |
What to include |
Your monthly amount |
| Housing and utilities |
Rent or mortgage, electricity, water, internet |
$_____ |
| Food and household needs |
Groceries, toiletries, cleaning supplies |
$_____ |
| Transportation |
Transit, fuel, insurance, maintenance |
$_____ |
| Health and obligations |
Healthcare, insurance, minimum debt payments |
$_____ |
| Irregular essentials |
Annual fees, repairs, seasonal costs |
$_____ |
| Flexible spending |
Dining out, entertainment, subscriptions |
$_____ |
Budget Smarter, Live Better: A Real-World Guide to Mastering Living Expenses | How Much to Budget for Living Expenses | Digital Download PDF Guide
View product
Let your actual costs lead
Subtract your monthly expense total from your take-home income. If money remains, give it a purpose: an upcoming bill, savings, or flexible spending. A percentage rule can be a starting point, but it cannot account for your particular rent, household needs, debt payments, or income stability.
If essentials exceed income, focus first on immediate needs and due dates. Explore hardship options and available support; small cuts to optional spending may not resolve a substantial gap.
Check the product’s listed specifications when evaluating let your actual costs lead.
Review, then adjust
Choose a tracking method you will use—a notebook, spreadsheet, or app—and check your spending once a week. At month’s end, compare your plan with what happened. Note one-off expenses before changing a category; if a cost keeps recurring, make room for it.
When you can, set aside a manageable amount for irregular bills. If income falls or a bill rises, revisit essentials first, then adjust flexible spending and savings contributions. We want your plan to remain usable as your circumstances change.
Build flexibility into the next month
When possible, set aside a manageable amount for irregular expenses, even if it starts small. That way, a predictable annual charge is less likely to feel like a surprise. If a bill rises or your income changes, revisit essential costs first, then revise flexible spending and savings contributions. Your budget should change with your circumstances.
To get started today, calculate your take-home income, fill in the living-expense table, and choose a date for your first weekly check-in.
Compare related options such as Handmade Mosaic Pattern Tempered Glass Basin with Waterfall Faucet Set to match features, dimensions, and use case before choosing.
Before choosing, compare the product details with your daily routine, available space, care needs, and preferred setup. The strongest option is usually the one that fits the intended use clearly and remains simple to clean, store, and check before repeat use.
It is also worth checking measurements, material notes, included parts, and compatibility details so the item matches the way it will be used after delivery.
FAQ
What is the best way to save money if I have a low income?
Identify essential bills and irregular costs first, then look for one feasible change or an assistance program. A small amount you can set aside repeatedly may be more useful than an unsustainable percentage target.
What is the best free budget tracking app?
The best choice is a free app you find easy to use and that lets you track the categories you care about. Compare current features, privacy terms, and any limits on the free version before choosing one.
How to budget with no income?
Prioritize immediate needs and due dates, contact bill providers about hardship options, and look into local assistance and income resources. A spending plan can help you track available cash, but it cannot replace income.
See if Budget Smarter, Live Better: A Real-World Guide to Mastering Living Expenses | How Much to Budget for Living Expenses | Digital Download PDF Guide fits your setup
View product




Leave a comment